

I’m more than a little overweight Financials. Circle of Competence is one thing, but it’s easy to take it too far. They aren’t quite as capital light as Tech, but they typically have high operating leverage, and can grow in their niche without the fear of a winner-take-all market. I feel sorry for those SaaS bros living under the fear that Masayoshi Son will give their competitor $500 million and squeeze them out. The current Artificial Intelligence zeitgeist has cast some doubt on the terminal value of many Financials, but I have a suspicion that at least some of these obsolescence fears are misplaced.
I have always liked Burford Capital (BUR), the market leading litigation finance company. Litigation finance can sound somewhat devious, the same is true for life settlements and reverse mortgages. But public companies receive practically no benefit to their stock price for pending litigation, so why not rely on the division of labor to outsource that job to a third party? A lawsuit can be frivolous, or it can bring our precedent-based legal system closer to a better approximation of justice. With their proprietary data set regarding which cases are more likely to succeed, Burford Capital can help firms choose which lawsuits to pursue and which to drop, without the incentive misalignment of law firms which are paid by the hour.
It is true that the US loses about 2.1% of GDP to lawsuits, more than triple the average of other developed nations. But that isn’t Burford Capital’s fault, the blame rests with State and Federal governments who spend their days redistributing wealth instead of legislating. And since the worship of power is humanity’s oldest religion, governments seem almost always able to pass the stigma away from themselves and onto private enterprise. But the threat always remains that congress will try to pass some sort of law banning litigation finance, or taxing it punitively, and the sycophantic media will convince petty and envious people to applaud the act.
My original writeup on Burford can be found here:
Coming to the nuisance with Burford Capital $BUR. What is going on?

What do you call a hundred lawyers on the bottom of the ocean? A good start.
I never built a huge position in Burford Capital, I wanted to, but I was prioritizing other financials such as Abacus Global Management (ABX), Beeline Holdings (BLNE), Finance of America Corporation (FOA), and Jackson Financial (JXN). When the time comes to take some profits in those positions, I hope Burford Capital is still cheap enough for me to want to buy.
The recent stock price collapse is due to the dismissal of the largest lawsuit on Burford’s balance sheet, a lawsuit against the sovereign nation of Argentina because they failed to offer to buyout all shareholders of YPF when they acquired a significant minority stake. I had originally thought that the government of Argentina would want to settle the lawsuit. But the IMF, who is happy to give money to any genocidal socialist dictator, refused to extend credit to Argentina. I realized that Javier Milei had no incentive to settle this affair. If settling the lawsuit doesn’t improve your credit rating, then why pay it? Sovereign nations can’t be compelled anyway. I don’t know if I ever typed that opinion out, but I shared it on one of the podcasts with The Royalty King, Ben Demase.
Without the uncertainty of such a large lawsuit on their balance sheet, I like Burford Capital a lot more. Just like any business, having a concentrated client portfolio brings additional risk, the business is healthier overall without the YPF lawsuit.
Buford Capital has a lot of advantages:
They are founder led with significant insider buying, although stock based compensation remains a bit high.
Their core business is still growing at a good pace.
They still have the largest proprietary data set in their industry, and that proprietary data is likely to remain unavailable to others as settlements almost always come with some sort of non-disclosure agreement.
They have smartly sold minority stakes to major law firms to align incentives so that they keep referring a pipeline of new lawsuits.
They have secured a partnership with a large Gulf State sovereign wealth fund to provide capital whenever an opportunity comes along that they can’t afford.
The disadvantages remains similar to a lot of other niche financial services companies:
A negative stigma surrounding the layman’s inability to appreciate the value added, which is common since Aristotle failed to recognize the value of time.
The lack of transparency surrounding Buford’s mark to market process, adjusting book value as certain legal milestones are achieved.
The upcoming possible mark to market loss that will come from marking down the YPF case.
The large stock based compensation.
The slow pace of working through the Covid backlog.
What remains?
What do you get for $1 billion with Burford trading at $4.72 per share? From a net income perspective, things don’t look great, a $62 million profit in 2025, down from $146 million in 2024. There is the overall growth story, acquiring $872 million worth of new case commitments in 2025, up from $627 million in 2024. But from a price to book perspective, before the collapse of the YPF lawsuit, at the end of 2025, Burford’s internal adjusted estimate of the value of their lawsuit book had risen from $4.5 billion in 2024 to $5.2 billion in 2025. The good news, Burford had excluded the Argentinian lawsuit from those book value figures.

The modeled realization estimate has grown with Burford’s book of lawsuits, rising from $3.4 billion at the end of 2021, to $5.2 billion today, and management is guiding for it to double by 2030. This represents a constant reinvesting of capital into the portfolio of the business, which masks a steady state earnings power. One would have to trust them on their marks, but if one does, being the market leader and taking the market before any serious competition gets organized only increases the moat of the proprietary data. If the market leader can model lawsuits more accurately, they should continue to get more business.
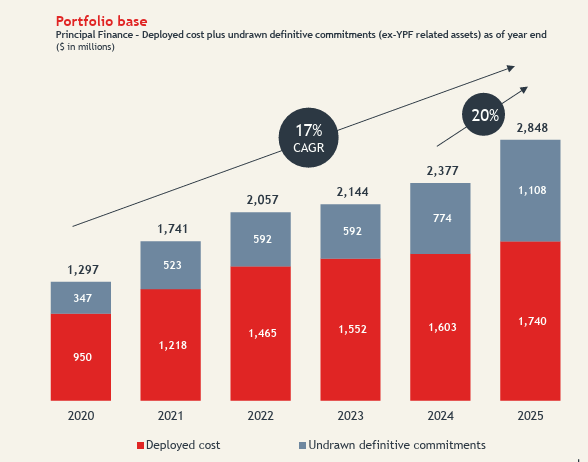
If you don’t want to look at modeled book value, you can look at capital deployed and future commitments to deploy capital. At the end of 2025, Burford had deployed over $1.7 billion, with another $1.1 billion committed. Around $117 million of this deployed capital is related to the YPF lawsuit, so Burford lost approximately 6.7% of their book value, and the market cut the stock price in half. This mark to cost book value hass a 17% compound growth rate, with a recent inflection higher. Using this metric still requires trust, is their proprietary data set worthwhile, are they good at choosing winning lawsuits?
Burford has a net lifetime loss rate of 10.2%, but full year 2025 only had a loss rate of 8%. This is a strong and tangible signal that they are getting better at choosing winning lawsuits. The ratio of cases that settle early has changed significantly with Covid, so it’s hard to compare apples to apples. Still, there is evidence of an improving and growing company for those with eyes to look for it.
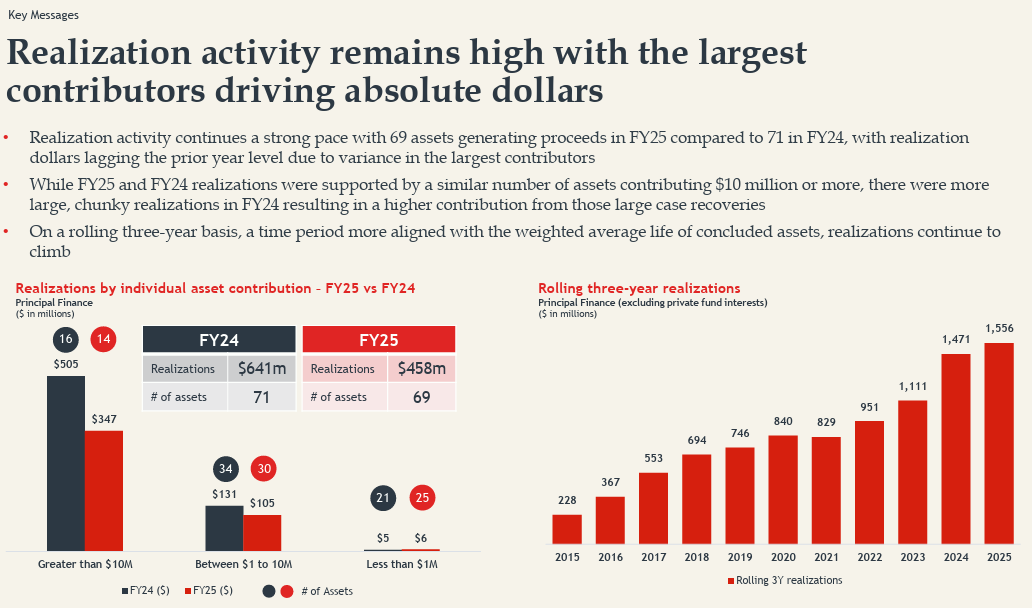
If you want to rely on a metric that requires much less trust, you can track cash received from lawsuits over time. Burford can mark their book in a black box, but cash is cash. Realizations are down in 2025 vs 2024, but again, Covid created a pig in a python problem which made 2024 abnormally large. Management is obviously trying to give the most optimistic picture by displaying a rolling three year cumulative figure, but that figure is still compounding at a 19% cumulative annual growth rate over the last 11 years. The average duration from deploying capital to a settlement is 2.5 years, and to a verdict is over three years. The inflection in the growth of the book should result in an inflection in this realization value eventually as well.
The market has lost confidence in Burford, and it takes a lot of trust to invest in an opaque niche financial who marks their own books. But I like them, there are a lot of signs that management is being prudent, the smart thing to do is to aggressively take more market share before competition gets organized. Some of the biggest criticisms surround capital allocation, why not buy back stock? The two cofounders, the CEO and CIO, own around 8.5% of the company, so their incentives are reasonably well aligned. I look forward to share buybacks, and the current valuation might prompt management to start pulling that trigger, but the lifetime Internal Rate of Return on litigation investments remains 26%. With such a high internal rate of return, I don’t blame Burford for not slamming the buyback button, but I also wouldn’t be surprised if that changes very soon.
Burford currently trades at less than half of tangible book, and growing niche financial services companies can easily trade at twice tangible book. There is room for a multiple re-rating to a four bagger, and continued aggressive growth. Twice tangible book would give a share price of $21 a share, but if it takes three years to re-rate to that valuation, the share price target will have grown to $33.63 by 2029.
Buford Capital (BUR) $4.72: $33.63 by mid 2029
BUR’s TBV per share is $11.18 with 219 million shares. $2.45 billion. Total. The YPF portion of TBV is $1.5 billion. They are going to mark that down significantly. If they mark it down 100% the TBV is about $1 billion, or $4.56/share. Trading at TBV with a solid business model and a potential YPF windfall is a good long term investment. It’s just not as good as you portray by not marking down YPF.
By the way:
I can't help but think the Trump Administration might have had its thumb on the scales for the YPF appeal decision, given how friendly Trump is with Milei in Argentina and how much control Trump exerts over the Judicial Branch.